
Rob Wilson, CFA, Director of Investment Strategy
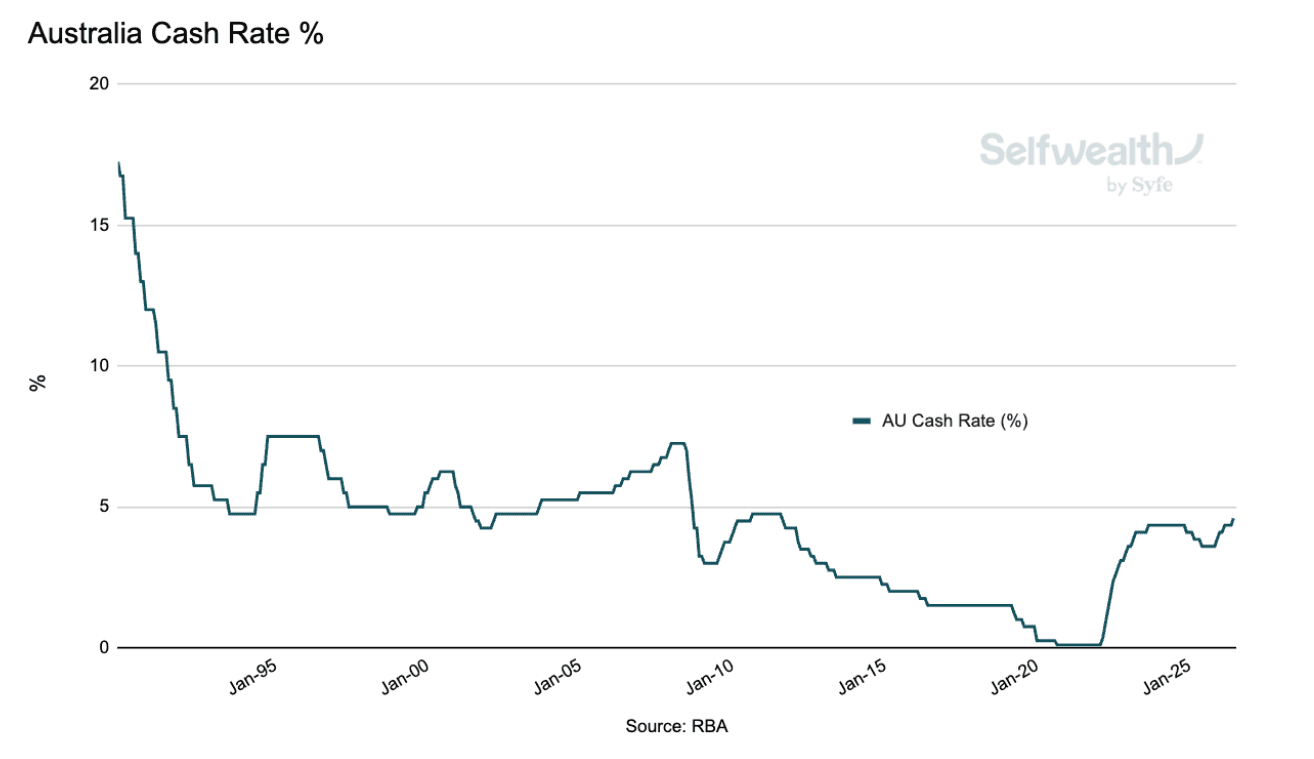
The Reserve Bank lifted the cash rate again this week, to 4.60%, its fourth increase this year, and one markets had firmly expected.
It caps a month in which most of the world’s major central banks have raised rates, though this looks more like the RBA tapping the brakes than slamming them on. Attention now turns to tomorrow’s inflation figures. Here is the wrap.
Key Takeaways
The RBA raised rates to 4.60%. The quarter-point rise was its fourth this year and was widely expected, after Governor Bullock signalled that unemployment needs to rise a little further to ease inflation.
Australia isn’t alone. The US Fed, the European Central Bank, and the Bank of Japan have all hiked in the past month, as high energy prices keep inflation above target around the world.
Markets barely blinked. The move was so well flagged that share markets took it in their stride, though rate-sensitive sectors like property and consumer discretionary remain the most exposed.
Inflation data is due tomorrow. August’s figures will help shape whether the RBA has more work to do though an extended run of hikes isn’t our base case.
The RBA Lifts the Cash Rate to 4.60%
The Reserve Bank raised the cash rate by a quarter of a percentage point to 4.60% this week, its fourth increase of the year. The decision was widely anticipated: in appearances the week before, Governor Michele Bullock had made the case plainly, describing the labour market as still ‘a bit tight’ and suggesting unemployment would need to sit somewhere in the 4.5–5% range to take the pressure off inflation. With underlying inflation still above target and the economy holding up, the Board judged another increase was warranted. For all that, this is the RBA tapping the brakes rather than slamming them on a gradual tightening rather than an emergency response. The next meeting for the RBA comes November 2.
Rates Are Rising Around the World, Not Just in Australia
Australia is far from alone. Over the past month the European Central Bank, the US Federal Reserve and the Bank of Japan have all lifted their policy rates — the Fed for the first time since 2023, and the Bank of Japan to its highest in more than three decades — as elevated energy prices keep inflation above target across much of the world. It is not only central banks pushing rates higher, though. Government bond yields, the interest rates set by markets rather than policymakers, have also climbed to multi-year highs globally, with the US 10-year yield touching around 5%, as investors weigh heavy government borrowing and sticky inflation. In that company, Australia is several taps ahead of the Fed, which has only just lifted its foot off the accelerator after a long stretch of holding steady. The upshot is that borrowing costs are rising across the board — for governments, businesses and households alike.
What It Means for Investors
Because the hike was so well flagged, share markets barely reacted. The parts of the market most sensitive to interest rates — property trusts and consumer-discretionary stocks among them — remain the most exposed if rates keep climbing. Markets still see scope for another RBA move late this year or early next, but an extended hiking cycle is not our base case: a market sell-off, an easing of geopolitical tensions that brings energy prices down, or rising costs weighing on hiring could all give the Bank reason to pause. In the meantime, one silver lining for investors is that cash and bonds are paying some of their best returns in years, offering a relatively defensive place to protect capital while the outlook stays uncertain.
Looking Ahead
The immediate focus is tomorrow’s inflation report — the August figures — which will give the first read on prices since the RBA’s move and help gauge how much further it may need to go. Beyond that, the forces behind this month’s global hikes — chiefly energy costs and the Middle East conflict — remain the key things to watch.
Key Dates to Watch
Australian inflation (August CPI) — tomorrow: The first price read since the RBA’s hike, and a guide to whether more tightening is coming.
US inflation (PCE) — 30 September: The Fed’s preferred inflation gauge, the first reading since its rate hike.
Global manufacturing PMIs — early October: A timely read on how factories and the broader economy are holding up as rates rise.
Oil & the Middle East — ongoing: Still the main driver of the energy-led inflation keeping central banks on the move.
Important disclaimer: SelfWealth Pty Ltd ABN 52 154 324 428 (“Selfwealth”) (AFSL 421789). The information contained on this website is general in nature and does not take into account your personal situation. You should consider whether the information is appropriate to your needs, and where appropriate, seek professional advice from a financial adviser and/or accountant. Taxation, legal and other matters referred to on this website are of a general nature only and should not be relied upon in place of appropriate professional advice. You should obtain the relevant Product Disclosure Statement for any product mentioned and consider its contents before making any decision.
Most Recent Articles